Half of CDC's Decarbonisation Comes From Reallocation, the Part Critics Dispute
Europe's public investors are being pressed to prove their climate targets cut real emissions, not just the carbon on their own books.
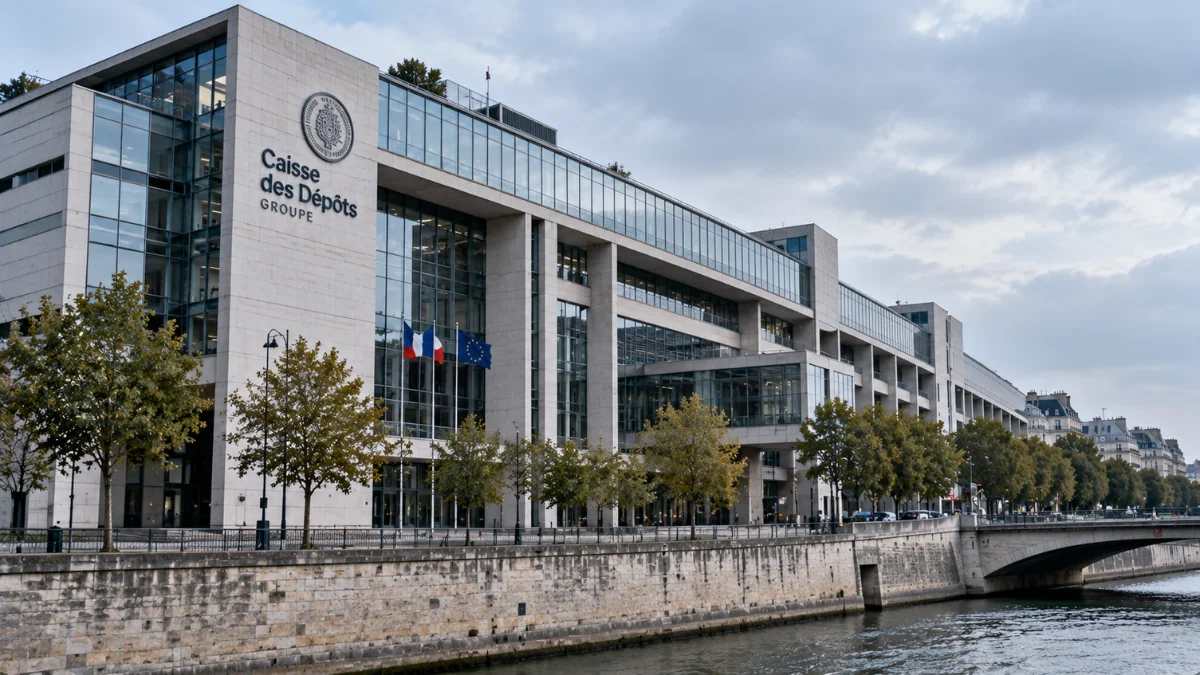
From 2027, Caisse des Dépôts will stop buying new bonds from oil producers, yet it will keep €4.8 billion of existing fossil fuel exposure, according to Les Echos. That combination places the French public investor at the centre of a sharpening argument over what net-zero portfolio targets actually deliver.
LSE Critique Puts Portfolio Targets on the Defensive
The challenge came this week at the PRI in Person conference in Amsterdam. Tom Gosling, Professor in Practice at the London School of Economics, argued that investor net-zero pledges encourage performative portfolio decarbonisation while real-economy emissions stay where they were. The position extends a recent LSE paper urging asset owners to prioritise policy advocacy over portfolio-level targets.
The critique lands on an industry already in retreat. Earlier in 2026, the UK's £40 billion People's Pension scrapped its 1.5°C-aligned portfolio target, arguing that a goal inconsistent with real-world progress adds risk for little benefit. Asset managers have also exited coalitions including Climate Action 100+ and the Net Zero Asset Managers initiative.
Caisse des Dépôts Attributes Half Its Progress to Reallocation
CDC, which manages roughly €320 billion drawn largely from regulated French savings products such as the Livret A, used the same stage to defend its 1.5°C goal. The institution said its portfolio emissions reductions have come in roughly equal parts from shifting capital between assets and from improvements inside investee companies. Its engagement now asks companies for interim milestones, not only long-dated targets.
Chief investment officer Josselin Kalifa presented the target as a governance tool first: "Setting a target was essential to get management's attention and support."
Oil Bond Exit Spares Gas Infrastructure and Existing Stakes
The policy update announced in September closes new debt channels to oil producers, TotalEnergies included, but carves out eligible green and sustainable bonds. It also converts CDC's cap on companies developing new exploration or production projects from a percentage into an absolute limit, so the exposure can no longer grow simply because the overall portfolio does. Direct financing of upstream gas projects has been excluded since 2022.
The gaps are equally specific. Developers of new LNG terminals and gas power plants fall outside the new restrictions, according to Reclaim Finance. CDC also keeps its current holdings, citing French energy sovereignty and its leverage as a voting shareholder.
Reallocation Is the Half Critics Will Contest
The equal split is the figure that matters most. Half of CDC's reported decarbonisation is precisely what Gosling's critique targets: when an investor sells or declines a bond, the issuer's emissions remain, now financed by someone else. The engagement half is easier to defend, but attributing a company's emissions cuts to investor pressure is hard to verify.
The absolute exposure cap is the more consequential change. Percentage caps let fossil holdings rise in step with assets under management; a fixed ceiling does not. The green bond carve-out, meanwhile, keeps a funding route open for oil majors willing to label their issuance.
The same test applies in India, where the national net-zero financing plan leans on banks for 83% of debt, as Climate Watch reported on 6 October. Indian lenders adopting fossil exclusions will need to show whether those exclusions reduce emissions or simply transfer ownership.
What to Watch
Implementation starts in 2027. The test is whether CDC reports its reallocation and engagement contributions separately each year, which would let outside analysts judge how much of its progress reaches the real economy. A second signal is whether other European asset owners follow People's Pension in abandoning top-down 1.5°C targets, or follow CDC in keeping them while narrowing fossil financing.
For more climate news click here